| |
FRIDAY MARKET UPDATE |
|
Good morning. The index ends the week near where it started, which is the least interesting thing that happened. |
■ | The 10-year hit a 20-year high. It closed Thursday at 5.192%, and December hike odds now sit at 95%. ■ | The data told two stories. Business activity ran at a five-year high while consumer sentiment came in at 47.8. ■ | Meta ran away with the week. Up nearly 15%, while the Russell 2000 gave back about 2.5% from Monday.
|
— Nathan Reed |
| | |
| |
| Gold & Macro — This Week in Metals |
|
| | |
Gold-Silver ratio 66.3 Gold led |
| |
Dollar (DXY) 101.02 +1.0% WoW |
|
|
Week's winner: Dollar | Week's loser: Silver |
|
Both metals lost ground to a dollar that has now climbed two weeks running — and silver gave back last Friday's pop in full, which tells you that move was about oil, not money. |
| | |
| |
|
A FLAT INDEX IS HIDING A VIOLENT ROTATION |
|
The S&P 500 sits at 7,711, about 0.7% below Tuesday. Underneath it, Oracle fell 6.44% Thursday after a force majeure notice over delays at its New Mexico data center, and is down roughly 20% this year. MGM Resorts dropped 9.98% when Barry Diller withdrew his buyout proposal. |
On the other side of the same week, Meta is tracking a near-15% gain and AI hardware names each added more than 2% today. That is not a quiet market. It is a market moving ten percent in single names while the average of those moves lands on zero. |
The Russell 2000 is the part I'd watch. It has given back about 2.5% since Monday, and small companies are where expensive money bites first — they borrow at floating rates and they borrow to survive, not to build. |
What to watch |
Whether the Russell keeps lagging into October. It is the cleanest read available on whether 5% money has reached the real economy, and it will show up there long before it shows up in the S&P. |
| | |
| |
|
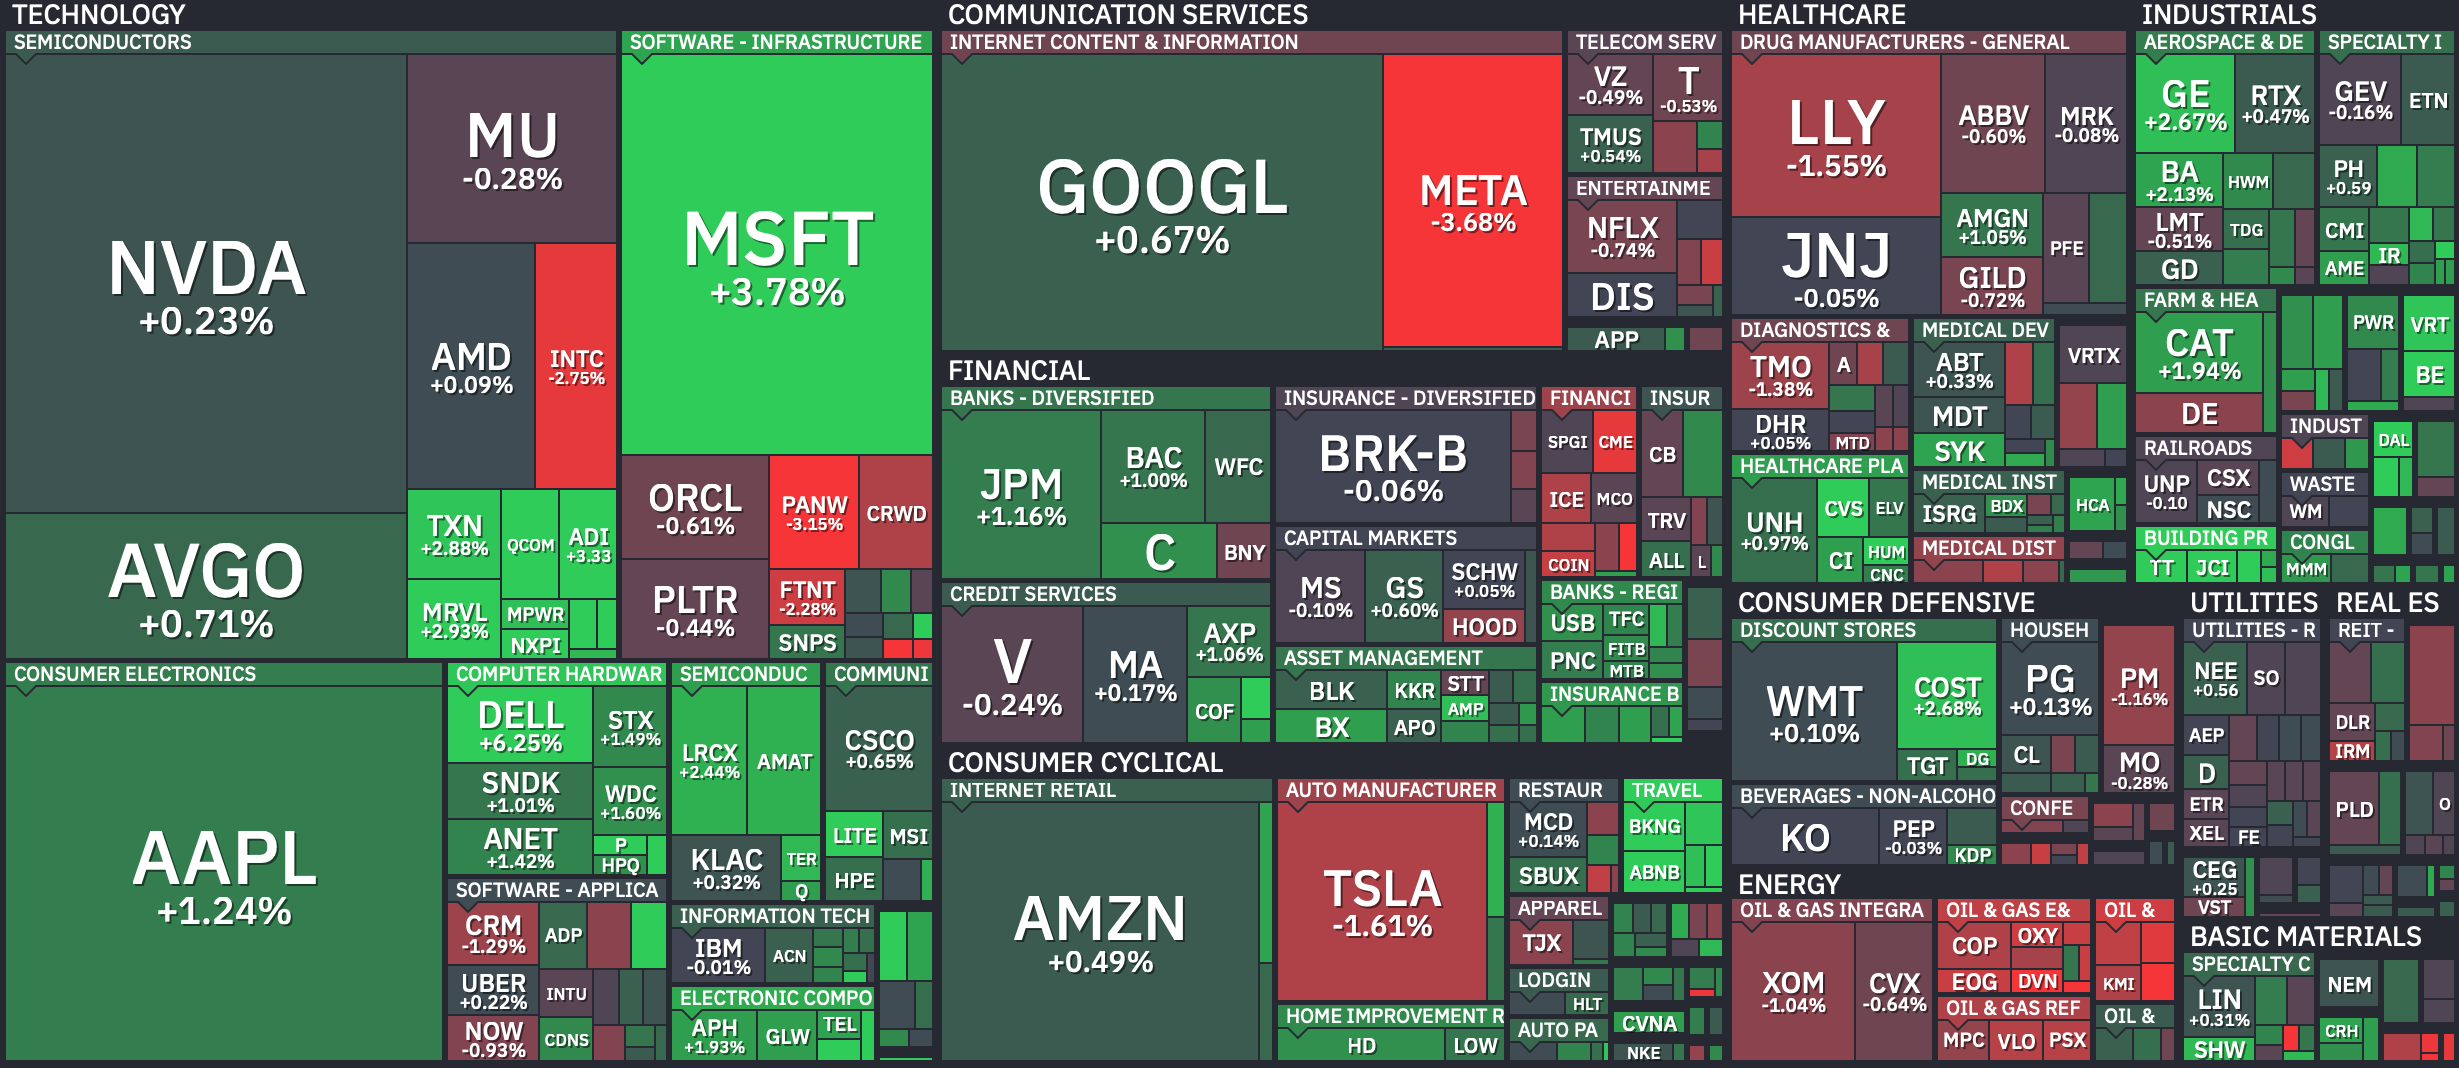 |
S&P 500 Heatmap — September 25, 2026. Credit: Finviz |
|
| | |
| |
|
"At 4.6%, consumers aren't forecasting the economy — they're reporting what they already paid. The Fed can dismiss a sentiment survey, but not that." |
| | |
| |
|
ORACLE, MGM, META |
Oracle $ORCL (▼ 6.44%) — issued a force majeure notice over delays at its New Mexico data center project. |
MGM Resorts $MGM (▼ 9.98%) — Barry Diller withdrew his buyout proposal, erasing the deal premium in one session. |
Meta Platforms $META (▲) — tracking a near-15% week after Connect, where it showed wearable agent controllers and new headsets. |
Micron $MU (▲ 2%) — rose with Marvell, SanDisk and Applied Materials as AI hardware caught a bid. |
Charles River Laboratories $CRL (▲ 5.37%) — the preclinical drug-testing firm, a useful proxy for biotech research budgets. |
Meta's weekly gain was still running at time of writing. For real-time data, I recommend monitoring Finviz. |
| | |
| |
|
OIL | Brent fell 2.51% to $103.93 on reports of a phased arrangement to reopen the Strait of Hormuz. |
INFLATION | Consumers' one-year inflation expectations jumped to 4.6% from 4.0%, the highest since June. |
FED | December hike odds reached 95% — the market now treats a second increase as near-certain. |
CHINA | Trump and Xi extended the trade truce to January 10; he claimed rare-earth and tariff wins, though analysts found no detailed terms. |
EARNINGS | TD Synnex fell 13% despite record earnings — positioning, not business. |
| | |
| |
|
On Wednesday I said the bond market had stopped trading energy and started trading growth. Thursday said something narrower. The five-year auction tailed and a same-day buyback failed, which is a supply problem, not a growth one. I had the direction right and the mechanism wrong, and the mechanism is the part that matters: a growth story resolves when the data cools, and a supply story doesn't resolve until somebody stops issuing. |
|
Two economies, one week. The bond market only listened to one of them. |
Nathan Reed | Profits & Insights |
Know someone who'd read this? Forward this email. It's free. |
| | |
|