| |
| |
TUESDAY MARKET UPDATE |
|
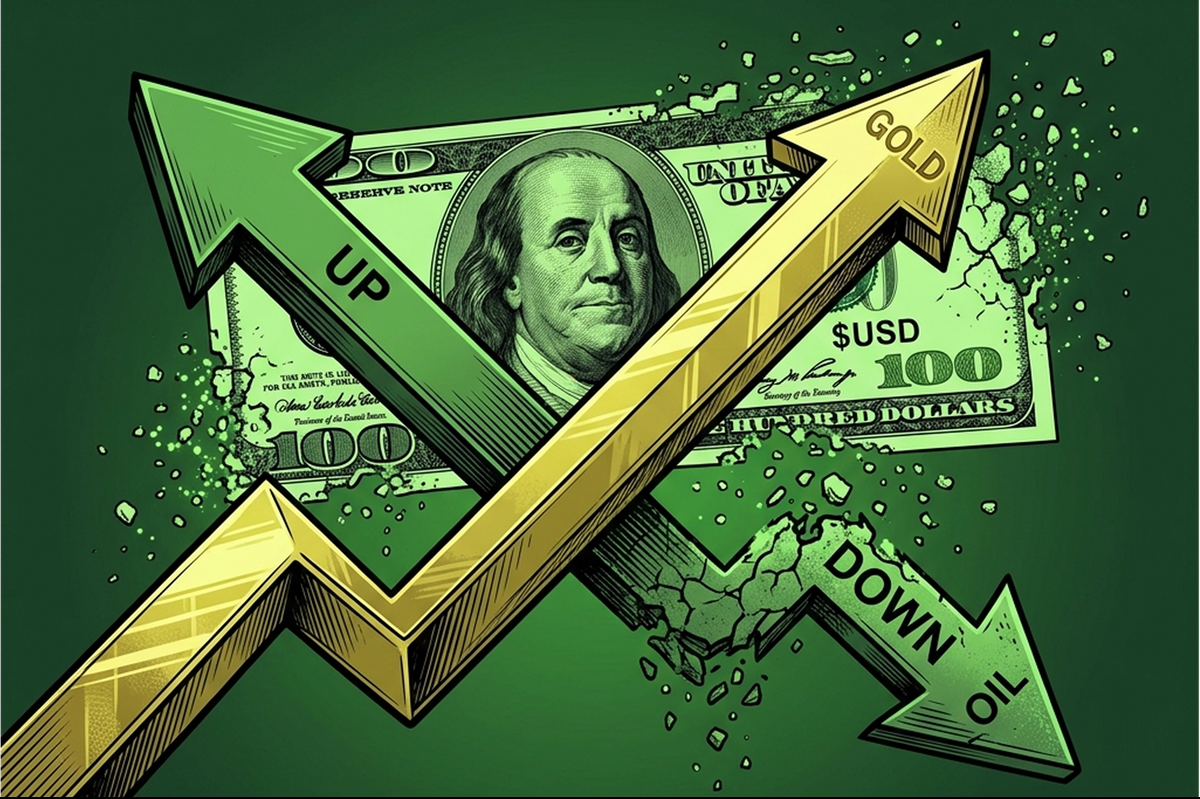
Bessent dropped the hammer. Sixty-plus entities sanctioned. Five sectors targeted: digital assets, technology, gold, aviation and shipping. He called it “economic asphyxiation”. A major financial institution may be sanctioned by Friday. China wasn't named — but wasn't exempted either. Beijing imports 80% of Iran's oil. Gold is at $4,650. Oil fell $2. Nvidia tomorrow. |
■ | Gold at $4,650 — 3-month high; debasement trade alive; Treasury may draw on cash account for more buybacks. ■ | Bessent: 60+ entities sanctioned — “economic asphyxiation of the regime”; major bank may be sanctioned by Friday; China not exempt. ■ Consumer confidence + new home sales today — Nvidia after close tomorrow; PCE Wednesday morning; Warsh Friday; the 72-hour gauntlet begins.
|
|
-Nathan Reed |
| |
|
| |
|
| |
| |
|
BESSENT SANCTIONED 60 ENTITIES. GOLD DIDN'T FLINCH. OIL DID |
|
Bessent delivered. More than 60 entities sanctioned across five sectors: digital assets, technology, gold, aviation, and shipping. He warned that any country doing business with Tehran would be cut off from the dollar system. A major financial institution may be sanctioned by Friday. China buys 80% of Iran's oil and was neither named nor exempted. That ambiguity is deliberate. It keeps Beijing guessing while giving gold exactly the uncertainty it feeds on. |
But here's the disconnect: gold hit a 3-month high. Oil fell $2. Sanctions are supposed to tighten oil supply and push crude higher. Instead, oil dropped on profit-taking while gold surged on the debasement trade. The market is saying the real risk isn't Iranian oil — it's the dollar system itself. The Treasury is buying its own bonds, sanctioning other countries' financial systems, and printing money to fund it all. Gold doesn't care about Hormuz anymore. It cares about the Fed balance sheet. |
FXStreet's analysis was blunt: the sanctions were “far from a D-Day scenario” and more of a “warning shot”. The specifics were few. The threats were large. Until we see actual enforcement — especially against Chinese entities — this is theater with real economic consequences. Gold knows the difference. That's why it's at $4,650 and rising. |
| |
|
| |
|
| |
| |
|
INTUIT, ZOOM, DKS. THE CONSUMER BEFORE THE STORM |
|
Consumer confidence drops this morning. After Walmart's 9% crash last Thursday, every consumer data point matters. Intuit, Zoom and Dick's Sporting Goods report today. Intuit tells you about small business spending. Zoom tells you about enterprise remote work. Dick's tells you about discretionary consumer health. Together, they paint a picture of America's spending capacity heading into the fall. Tomorrow is Nvidia and PCE — the biggest 24 hours of the quarter. |
The S&P fell 0.3% Monday. The Nasdaq dropped 1%. Semiconductors have been bleeding for a week — the VanEck Semiconductor ETF is down 4%. This is the backdrop into which Jensen Huang speaks tomorrow. If Nvidia beats and guides higher, the selloff reverses and the S&P has a path to 8,000. If Nvidia disappoints — even slightly — the rotation into gold, energy and defensives that started last week becomes a stampede. |
What to watch: |
| |
|
| |
|
| |
| |
|
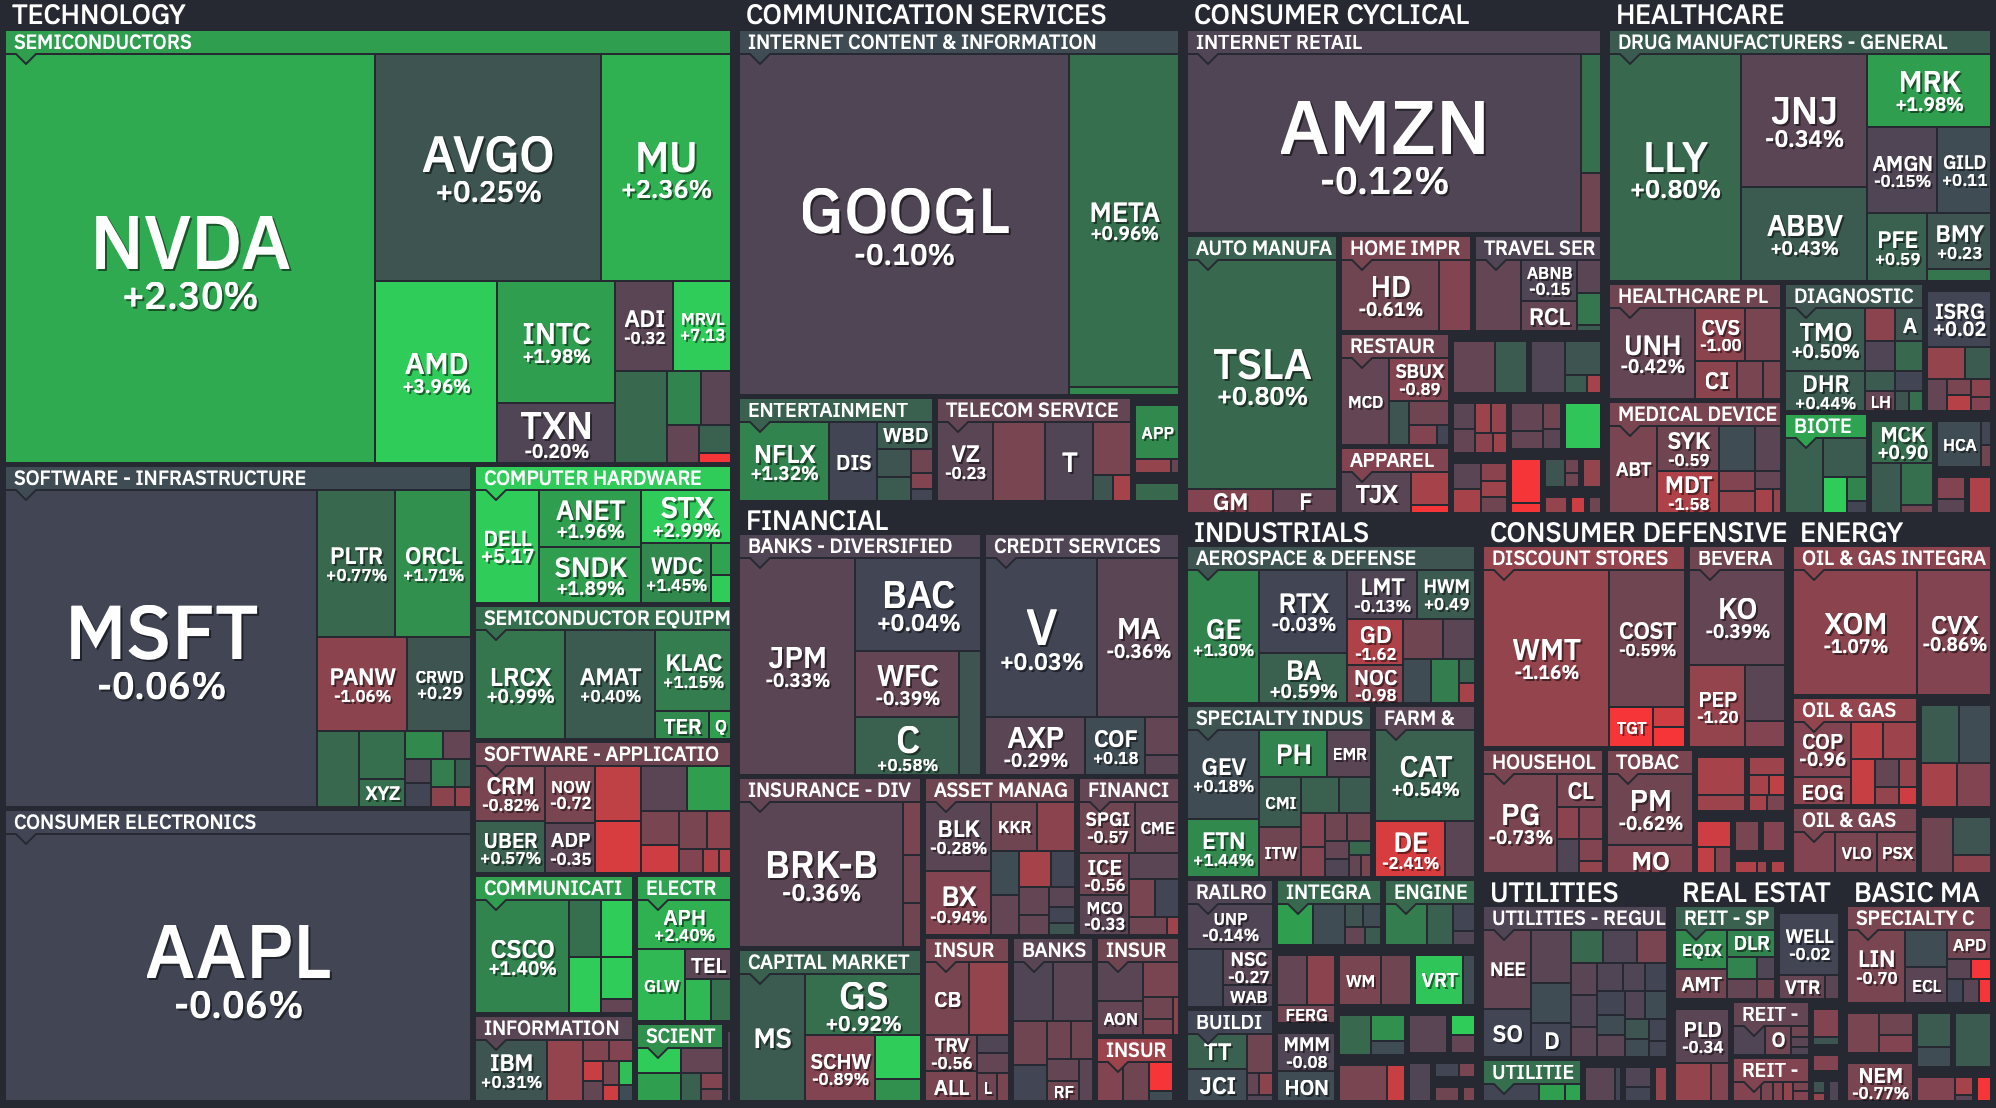 |
S&P 500 Heatmap — August 25, 2026. Credit: Finviz |
|
| |
|
| |
|
| |
| |
|
“Bessent sanctioned 60 entities and called it “economic asphyxiation.” Gold rose. Oil fell. If the market believed the sanctions would tighten supply, oil would be at $100 and gold would be flat. Instead, gold hit a 3-month high and crude dropped $2. The market isn't trading sanctions as a supply story. It's trading them as a dollar credibility story. When the US weaponizes its currency against 60 entities in one afternoon, the rest of the world takes notes — and buys gold” |
| |
|
| |
|
| |
| |
|
NVIDIA, INTUIT, DOLLAR TREE |
Nvidia $NVDA ( ▲ 2.27% ) — the AI referendum; Rubin chip timeline + China guidance + capex trajectory; the single most important earnings report of the quarter. |
Intuit $INTU ( ▼ 2.56% ) — small business spending proxy; TurboTax + QuickBooks + Mailchimp; the domestic economy health check. |
Dollar Tree $DLTR ( ▲ 4.01% ) — the ultimate trade-down play; if Dollar Tree is gaining customers from Walmart, the consumer squeeze is deeper than the data shows. |
Workday $WDAY ( ▼ 2.12% ) — enterprise HR/finance software; hiring signals + AI adoption in back-office; the labor market software read. |
Franco-Nevada $FNV ( ▼ 0.29% ) — gold royalty model thriving at $4,650 spot; expanding margins without mining risk; the smart-money metals play. |
For real-time data, I recommend monitoring Finviz. |
| |
|
| |
|
| |
| |
|
GOLD | Gold: $4,650 — 3-month high; up 14% in August; the debasement trade is now the dominant narrative; Treasury buybacks fueling the bid. |
SANCTIONS | Bessent: 60+ entities sanctioned — five sectors targeted; “economic asphyxiation”; major bank sanction possible by Friday; China not exempt. |
OIL | Oil: fell $2 Monday — profit-taking before sanctions; Brent $91.50; the market doesn't believe the sanctions actually disrupt supply. |
FED | September hike: 36% probability — 64% hold; Friday's PCE is the final data point; Warsh's speech is the final signal before the Sept 15-16 FOMC. |
SEMIS | Semis: −4% last week — VanEck Semiconductor ETF selling off into Nvidia; momentum stocks down 4%; tech in a mini-correction ahead of the big report. |
| |
|
| |
|
| |
| |
|
Consumer confidence this morning. Intuit tonight. PCE + Nvidia tomorrow. GDP Thursday. Warsh Friday. Gold at $4,650. Three days. Stay sharp. |
Nathan Reed | Profits & Insights |
| |
|
| |
|
|